Gnrc Drops 15.3% In The Past Month. Is The Selloff A Buying Chance?
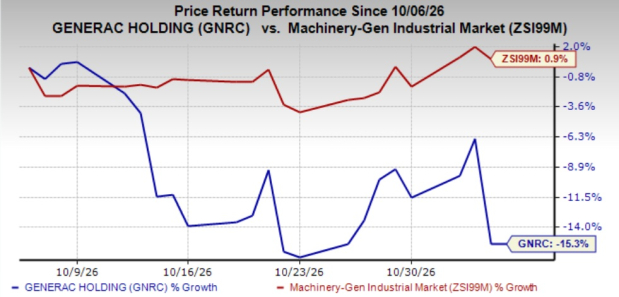
Generac Holdings Inc. GNRC has fallen 15.3% over the month even as several operating measures improved. The pullback leaves investors weighing whether stronger earnings and expanding data center demand can support a rebound.
Image Source: Zacks Investment Research
The counterpoint is execution. Revenue missed expectations in the third quarter, margins face mix pressure and the company is scaling manufacturing capacity quickly.
GNRC’s Pullback Meets a Stronger Growth Backdrop
Generac reported third-quarter 2026 net sales of $1.29 billion, up 16% year over year. Adjusted earnings rose 38.8% to $2.54 per share and beat the Zacks Consensus Estimate by 6.7%.
Sales, however, missed the consensus mark by 1.5%. That gap helps explain why improving earnings do not remove all investor caution, particularly with the business mix changing rapidly.
Generac’s Data Center Backlog Reshapes the Story
Data centers have become a major growth driver. Generac generated more than $100 million of data center revenues in both the second and third quarters, while backlog reached about $4.5 billion in the third quarter.
Management now expects nearly $500 million of data center revenues in 2026 and more than $2 billion in 2027. Cummins Inc. CMI is also expanding its data center power exposure through generator and energy-storage projects, underscoring the scale of industry demand.
GNRC’s Residential Recovery Adds a Second Engine
Residential revenues rose 9% year over year to $744 million in the third quarter. Home standby generator shipments increased at a mid-teens rate as outage activity returned to more normal levels.
Generac’s residential dealer network expanded to nearly 9,900, while in-home consultations increased sharply. Those indicators provide a second growth avenue beyond data centers, although residential demand remains sensitive to weather and outage activity.
Generac’s Margin and Execution Risks Could Persist
Third-quarter gross margin improved to 39.9%, but management expects fourth-quarter gross margin of 37-38%. A larger contribution from lower-margin data center sales and other inflationary pressures are expected to drive the sequential decline.
Tight high-horsepower diesel engine availability, capacity-ramp risk and capital spending of roughly 4-4.5% of 2026 revenues add execution pressure. Eaton Corporation plc ETN is also expanding manufacturing tied to data center infrastructure, highlighting how suppliers across the market are investing to meet rising demand.
GNRC’s Momentum Signals Support a Tactical Rebound
The pullback sits alongside accelerating earnings and backlog, but it is not a simple value call. Shares were still up 23.1% over the past year despite the recent decline. Manufacturing execution and mix-driven margin pressure could remain important swing factors.
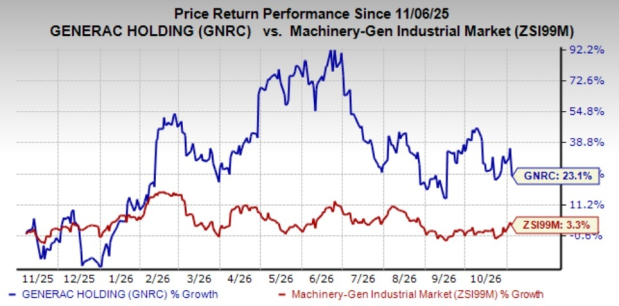
Image Source: Zacks Investment Research
GNRC currently carries a Zacks Rank #2 (Buy), along with a Momentum Score of A, Growth Score of B and VGM Score of B. Those readings favor the stock’s near-term setup when paired with a top Zacks Rank.
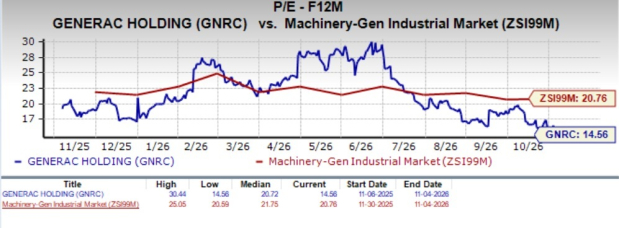
Image Source: Zacks Investment Research
The Value Score of C is less emphatic. GNRC trades below some historical and industry earnings multiples, but other valuation measures are not uniformly inexpensive. The combination supports selective optimism rather than treating the 15.3% decline as an automatic bargain.
You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Research Chief Names "Single Best Pick to Double"
From thousands of stocks, 5 Zacks experts each have chosen their favorite to skyrocket +100% or more in months to come. From those 5, Director of Research Sheraz Mian hand-picks one to have the most explosive upside of all.
This company targets millennial and Gen Z audiences, generating nearly $1 billion in revenue last quarter alone. A recent pullback makes now an ideal time to jump aboard. Of course, all our elite picks aren’t winners but this one could far surpass earlier Zacks’ Stocks Set to Double like Nano-X Imaging which shot up +129.6% in little more than 9 months.
Free: See Our Top Stock And 4 Runners UpThis article originally published on Zacks Investment Research (zacks.com).
Popular Products
-
 Pet Oral Repair Toothpaste Gel
$59.56$29.78 -
 Opove M3 Pro 2 Electric Massage Gun
$901.56$450.78 -
 Portable Electric Abdominal Massager ...
$45.56$22.78 -
 Bee Venom Capsules for Joint Support ...
$43.56$21.78 -
 Ashwagandha & Black Cumin Seed Oil
$43.56$21.78