Will Davita's Q3 Earnings Reflect Improving Treatment Growth Trends?

DaVita Inc. DVA is scheduled to report third-quarter 2026 results on Oct. 29, after the closing bell.
In the last reported quarter, the company’s earnings per share (EPS) of $4.02 surpassed the Zacks Consensus Estimate by 0.3%. Over the trailing four quarters, its earnings beat the Zacks Consensus Estimate on three occasions and missed once, delivering an earnings surprise of 0.1%, on average.
Let’s check out the factors that have shaped DVA’s performance prior to this announcement.
Factors Likely to Shape DaVita’s Q3 Results
DaVita’s third-quarter 2026 performance is likely to have benefited from improving treatment volumes and a favorable calendar comparison. Management expects full-year treatment growth near the upper end of its previous 25-50 basis-point guidance range, supported by better-than-expected patient mortality trends and improving operating performance. The third quarter has a favorable year-over-year calendar effect, which is expected to support reported treatment growth. However, a weaker commercial payor mix could continue to constrain revenue growth and profitability.
Revenue per treatment (RPT) is likely to have remained under pressure. Although higher reimbursement rates should have provided support, the expiration of Affordable Care Act subsidies and lower phosphate binder revenues are expected to have weighed on the commercial payor mix and overall reimbursement. Management expects full-year RPT growth of 1-2%, implying a bit of negative growth in the second half of 2026 compared with the prior-year period.
Cost management is expected to have improved in the quarter. Patient care costs per treatment declined sequentially in the second quarter, supported by labor productivity, operating leverage and lower phosphate binder costs. These benefits could have continued into the third quarter, although higher employee benefit expenses and other medical costs remain potential headwinds. General and administrative expenses are also likely to have reflected investments in technology and operational capabilities. Management expects full-year total cost per treatment growth of 1.25-2.25%.
DaVita reported adjusted operating income of $40 million in the second quarter for Integrated kidney care (IKC) compared with an adjusted operating loss of $19 million in the first quarter. Growth was primarily driven by the timing of revenue recognition. IKC is expected to remain the biggest driver of the anticipated $50-$100 million sequential increase in adjusted operating income from the third to the fourth quarter. This suggests that revenue timing could have limited IKC's contribution to third-quarter results, despite continued progress in managing care costs and expanding the business.
DaVita maintained its 2026 guidance for adjusted operating income of $2.15-$2.25 billion and adjusted EPS of $14.10-$15.20 following its second-quarter results. Investors will watch whether treatment growth and cost discipline can offset reimbursement headwinds and support the company’s full-year targets.
DVA’s Estimate Picture
For third-quarter 2026, the Zacks Consensus Estimate for revenues is pegged at $3.53 billion, implying an improvement of 3.2% from the prior-year quarter’s reported figure.
The consensus estimate for EPS is pegged at $3.78, indicating an uptick of 50.6% from the prior-year period’s reported number.
What Our Model Suggests About DaVita
Per our proven model, a stock with a Zacks Rank #1 (Strong Buy), 2 (Buy), or 3 (Hold), along with a positive Earnings ESP, has higher chances of beating estimates. However, this is not the case here, as you can see below.
DaVita’s Earnings ESP: DVA has an Earnings ESP of 0.00%. You can uncover the best stocks to buy or sell before they are reported with our Earnings ESP Filter.
Zacks Rank of DVA:The company currently carries a Zacks Rank #3. You can see the complete list of today’s Zacks #1 Rank stocks here.
DVA’s Share Price Performance
Year to date, DaVita’s shares have surged 62%, outperforming the Medical - Outpatient and Home Healthcare industry’s 24.4% rise, the Zacks Medical sector’s 4.9% gain and the S&P 500’s 10.6% growth.
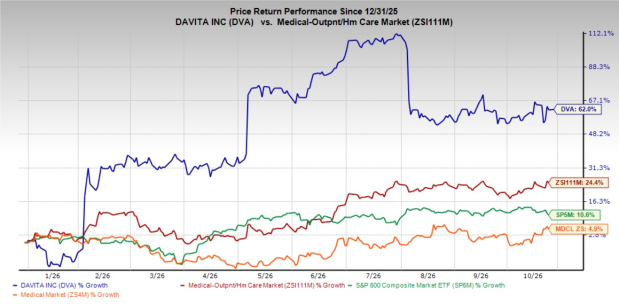
Image Source: Zacks Investment Research
DaVita’s peers like Aveanna Healthcare Holdings Inc. AVAH, Quest Diagnostics DGX and Encompass Health EHC have underperformed it. AVAH, DGX and EHC’s shares have gained 61.3%, 40% and 16.9%, respectively, in the year-to-date period.
Radical New Technology Could Hand Investors Huge Gains
Quantum Computing is the next technological revolution, and it could be even more advanced than AI.
While some believed the technology was years away, it is already present and moving fast. Large hyperscalers, such as Microsoft, Google, Amazon, Oracle, and even Meta and Tesla, are scrambling to integrate quantum computing into their infrastructure.
Senior Stock Strategist Kevin Cook reveals 7 carefully selected stocks poised to dominate the quantum computing landscape in his report, Beyond AI: The Quantum Leap in Computing Power.
Kevin was among the early experts who recognized NVIDIA's enormous potential back in 2016. Now, he has keyed in on what could be "the next big thing" in quantum computing supremacy. Today, you have a rare chance to position your portfolio at the forefront of this opportunity.
See Top Quantum Stocks Now >>This article originally published on Zacks Investment Research (zacks.com).
Popular Products
-
 Classic Oversized Teddy Bear
$23.78 -
 Gem's Ballet Natural Garnet Gemstone ...
$171.56$85.78 -
 Butt Lifting Body Shaper Shorts
$95.56$47.78 -
 Slimming Waist Trainer & Thigh Trimmer
$67.56$33.78 -
 Realistic Fake Poop Prank Toys
$99.56$49.78